The DO Loop
Statistical programming in SAS with an emphasis on SAS/IML programs

The classical multivariate normal (MVN) distribution is a standard model for correlated data. It is a simple model, it is easy to fit the MVN model to data, and the parameters in the model (locations and correlations) are intuitive. Of course, normality is a strong assumption that is not always
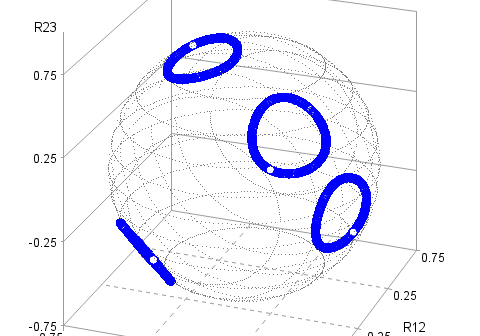
A previous article discusses how to generate a random correlation matrix. On average, in a random correlation matrix, half of the off-diagonal entries are negative and half are positive. For any realization, the proportion of negative correlations might be greater than (or less than) half. This is in contrast to
In a previous article, I implemented an algorithm due to Niels Waller (TAS, 2020) that uses the method of alternating projections (MAP) to generate random correlation matrices that have a specified set of eigenvalues. The algorithm is iterative, and the MAP method is not guaranteed to converge, although Waller claims