The DO Loop
Statistical programming in SAS with an emphasis on SAS/IML programs

I've been working on a project that uses quasi-Monte Carlo (QMC) techniques to estimate probabilities for multivariate normal (MVN) distributions on finite or infinite rectangular regions. The goal is to enable SAS users to compute these probabilities accurately and efficiently. My implementation is based on a numerical technique called the
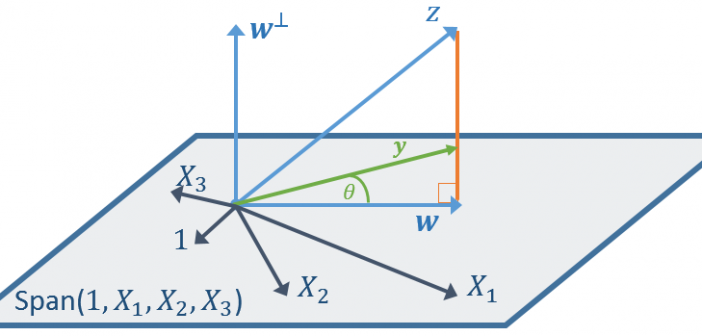
One of the great algorithms of linear algebra is the Gram-Schmidt orthogonalization process, which enables you to construct an orthogonal basis for a linear subspace from any set of linearly independent vectors that span the subspace. The Gram-Schmidt process is the basis for the QR decomposition in numerical linear algebra,

A previous article describes the nonnegative matrix factorization (NMF). You can use the NMF to reveal important features in data that can be used to reduce the dimensionality of the problem. NMF is useful when the data are nonnegative, such as counts or pixel values in an image. The goal